

Am I spending more on travel than other Singaporeans?
Financial Planning 101: How your annual holiday spending compares with other Singapore households.
What this article covers
- How much Singapore households spend on overseas holidays, including a more useful benchmark for households that actually travel.
- How destination, income and travel frequency affect what you spend, and why one national average does not tell the whole story.
- How much of your income you might reasonably spend on holidays, including an international 5% to 10% rule of thumb and Singapore financial planning guidance.
- How to tell whether you can actually afford your travel budget, after accounting for savings, insurance protection and other financial priorities.
For many Singaporeans, overseas travel is rarely a single large annual expense. Instead, we make several smaller expenses throughout the year.
- A flight to Bangkok
- A family holiday to Japan there.
- A quick weekend across the Causeway in between.
Which makes it slightly more difficult to track exactly how much you really spending on holidays per year.
But perhaps the more interesting question is: are you spending more than other Singaporeans? The latest data gives us a useful place to start.
The headline figure: Singapore households spent an average S$3,558 a year on overseas travel
According to the last Singapore Department of Statistics (SingStat) Household Expenditure Survey (HES) done in 2023, households in Singapore spend an average of S$297 a month on overseas travel, or about S$3,558 a year.
SingStat conducts this survey once every five years, with the next report due in 2028.
Two definitions matter before you compare yourself with it:
- What counts: Air, coach and ferry fares, accommodation, package tours, travel insurance and out-of-pocket expenses such as food and transport abroad. The trip must last at least 24 hours or include an overnight stay overseas.
- What does not count. Business trips are excluded. So are day trips, like driving or taking the train across to Johor Bahru.
Why S$3,558 is probably much lower than what most travellers actually spend
There is another arguably more important caveat to this figure: The S$297 monthly average is calculated across all households in Singapore, regardless of whether they travelled or not.
In 2023, only 55.3% of resident households recorded overseas travel expenditure. Extrapolating both these data points, we get: S$297 ÷ 55.3% × 12 = approximately S$6,445 a year spent on average by Singaporean households on travel. (This is a Lifepedia calculation based on SingStat figures, rather than a separately published SingStat statistic.)
Additionally, given the circumstances surrounding travel prior to the HES, it is reasonable to predict this number could be higher in the present day.
SingStat itself notes that the survey's 12-month recall period covered travel spending during 2022 and 2023, when international travel was still recovering from COVID-19 restrictions.
Another important factor: destination matters
Among households that incurred expenditure on travel to each region, the average annual spending in 2023 by destination was:
- Southeast Asia: S$2,500
- Rest of Asia: S$6,305
- Australia and New Zealand: S$7,078
- America and Canada: S$11,437
- Europe: S$11,723
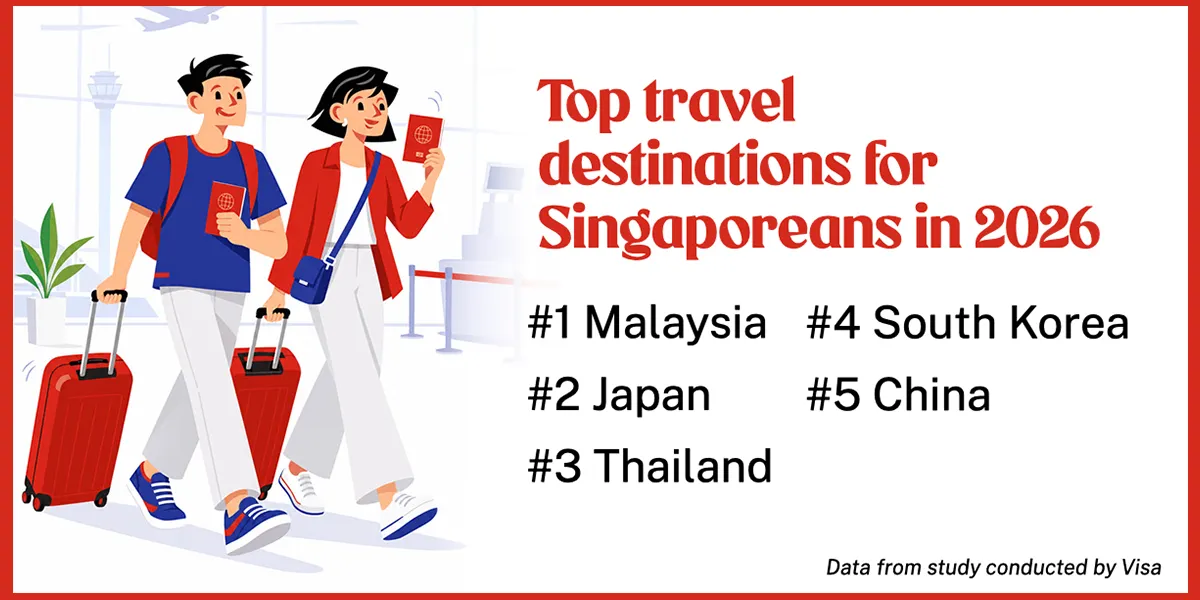
Singapore households were also far more likely to travel within Asia. In 2023, 38% recorded expenditure on travel to Southeast Asia and 20.9% elsewhere in Asia. Only 6% recorded European travel expenditure.
That helped to pull the overall Singapore expenditure average down. So, if long-haul holidays are your preference, being above the national travel-spending average should not be particularly surprising.
Singaporeans are also travelling more often
The 2023 spending figures need to be viewed alongside another change: Singaporeans are travelling more frequently.
As at the end of June 2025, 84.1% of Singapore citizens had made at least one overnight overseas trip during the preceding 12 months, according to newer SingStat data.
- Among those who travelled, the median number of overnight trips was four, up from three in 2015.
- The proportion making six or more overnight trips rose from 22.8% to 33.5% over the same decade.
This matters because your travel expenses rise even if none of your holidays are particularly extravagant. For instance, four S$2,000 trips will add up to S$8,000.
Add a couple of short regional breaks to one major family holiday and your travel budget can move into a five-figure sum without any individual booking feeling especially expensive.
That is why an annual travel budget is more useful than asking whether your most recent holiday costs too much.
But how much are Singaporeans spending relative to their income?
Looking at absolute dollar amounts can only get us so far. A household earning S$80,000 a year and spending S$8,000 on travel is making a very different financial commitment from a household earning S$250,000 and spending the same amount.
SingStat's data gives us an interesting way to look at this. In 2023, average monthly overseas travel expenditure across all households ranged from S$95 among the lowest-income 20% to S$642 among the highest-income 20%.
But higher-income households were also far more likely to incur travel expenditure. Only 31.2% of households in the lowest 20% recorded overseas travel spending, compared with 76.9% of those in the highest 20%.
Adjusting for those participation rates produces the following estimates.
Lowest 20% of households
21st to 40th percentile
41st to 60th percentile
61st to 80th percentile
Highest 20% of households
These travel spending figures and percentages are Lifepedia calculations based on published SingStat data and are intended as broad comparisons only. Household income includes employer CPF contributions and income from other sources, and is not equivalent to take-home pay.
These numbers should be treated as indicative only, but they do hold an interesting observation: Higher-income households appear to be able to spend considerably more money on holidays while using a smaller proportion of their income to do so.
- The highest-income travelling households spent around S$10,000 a year, almost three times the amount spent by travelling households in the lowest income quintile.
- Yet the indicative expenditure-to-income ratios move in the opposite direction.
That is why comparing your S$10,000 travel budget with somebody else's S$5,000 budget tells you very little about which household is stretching its finances further.
How much of your income should you spend on holidays?
There is no official guideline on how much you spend on your holidays relative to your income.
However online reports, quoting financial experts, generally list 5% to 10% of take-home income for holidays as a starting point. These reports also stress that the appropriate amount is still highly dependent on your own present financial wellbeing (Do you have any existing debts? Will you have to save money for an upcoming major expense?).
If we were to do a simple calculation: If your household takes home S$8,000 a month, or S$96,000 a year,
- 5% = S$4,800 a year for travel
- 7.5% = S$7,200
- 10% = S$9,600
For a household taking home S$12,000 a month:
- 5% = S$7,200
- 7.5% = S$10,800
- 10% = S$14,400
This does not mean 10% is a maximum, or that spending less than 5% is automatically financially prudent. It is simply another way to put the number into context.
Think about what travel is competing with
Rather than prescribing an annual holiday budget, what could be more useful is to look at your finances as a complete picture.
The 50/30/20 budgeting rule offers a simple framework. It divides take-home income into three broad buckets:
- 50% for needs, such as housing, groceries, utilities and transport
- 30% for wants, such as dining out, entertainment, shopping and holidays
- 20% for savings and financial goals, such as emergency savings and retirement
This provides a useful way to put holiday spending into perspective.
- Suppose your household takes home S$10,000 a month.
- Under the 50/30/20 rule, around S$3,000 a month, or S$36,000 a year, would be available for all your wants.
- If you spend S$12,000 a year on holidays, travel alone will use up one-third of your discretionary budget.
- That may be perfectly reasonable if travelling is important to you, but it also means you get to spend significantly less on eating out, shopping, entertainment or other wants.
- If a large travel budget comes on top of significant spending in all those other areas, you may find yourself dipping into the money intended for needs or savings.
This also helps put the commonly cited 5% to 10% of take-home income for holidays into context.
- Spending 10% of your income on travel does not necessarily mean you are spending too much.
- But under a 50/30/20 framework, it would use up around one-third of your entire 30% wants budget.
The more useful question is therefore not simply whether you spend 5%, 8% or 10% of your income on holidays, but how much of your discretionary spending you want travel to take up, while still leaving enough for your essential expenses, savings and other financial priorities.
Crucially, you should also know that the 50/30/20 rule is more of a “rule-of-thumb” rather than an actual principle. Housing costs, children, debt repayments and other commitments can easily change the required split for your household.
Nonetheless, the key lesson here is: fund the holiday from the part of your budget meant for wants, rather than “borrowing” from the money you need for today or are setting aside for tomorrow.
So are you actually spending too much on holidays?
Imagine two households that each spend S$10,000 a year on travel.
- The first has built an emergency fund, pays its credit cards in full, regularly saves and invests, has reviewed its insurance needs and deliberately puts money aside every month for holidays.
- The second pays for flights using credit, dips into emergency savings for hotel bills and stops saving whenever a major trip comes around.
- Only one may be able to comfortably afford it.
Instead of focusing on whether your travel budget is above average, you can consider asking:
1. Are you paying for this year's holiday with next year's income?
There is a difference between using a credit card as a payment method and relying on credit to make a holiday affordable.
If you cannot pay the bill in full without dipping into emergency savings, the original holiday price may not reflect what the trip ultimately costs you.
2. Are your emergency savings still intact?
A holiday is a planned expense. An emergency fund is meant for the expenses you cannot plan for.
Most guidelines recommend building emergency savings of at least three to six months of expenses. Using your emergency funds to finance holidays can leave you financially exposed when a genuine unexpected expense occurs.
3. Are expensive holidays crowding out your longer-term goals?
Travel may be important to you, but so might buying a home, funding your children's education, investing for retirement or simply building greater financial flexibility.
If every holiday means suspending your regular savings or investments for several months, the cost of the trip is not just what appears on your credit card statement, but what that money could otherwise have been doing for your future.
4. Is your financial protection keeping pace with your lifestyle?
Most of us probably may not choose buying insurance over enjoying a holiday.
But spending on discretionary experiences instead of addressing major financial risks to yourself or your dependants can be risky.
A household that could once comfortably prioritise holidays may need to rethink how their discretionary spending once they start having children, taking on a mortgage or supporting ageing parents.
If you are unsure how your existing protection fits alongside your savings, investments and lifestyle goals, you could consider reviewing your financial plan or speaking to a financial representative.
Do not forget to protect the holiday itself
Besides airfare and hotel bookings, travel insurance should belong in your holiday budget too.
Travel insurance can cover risks such as:
- trip cancellation caused by serious illness
- accidental injury
- overseas medical expenses
- travel disruption
- lost belongings
How much you spend on travel insurance depends on where and how you travel.
- For instance, if you head somewhere with limited access to medical facilities, you may want to pay particular attention to medical treatment and emergency evacuation coverage.
- Frequent travellers can also consider whether annual cover is more suitable than purchasing separate single-trip policies for every journey.
Benefits, geographical limits, maximum trip durations and exclusions differ between policies, so it is worth checking whether your cover fits the type of holiday you are actually taking.
Frequently asked questions
GREAT TravelCare
From quick getaways to longer trips, get 24-hour worldwide support for medical emergencies to travel assistance.
Let us match you with a qualified financial representative
Our financial representative will answer any questions you may have about our products and planning.