



What happens to your insurance if you move overseas
Financial Literacy 101: Moving abroad? Some insurance follows you, while other cover can change significantly.
What this article covers
- Which insurance policies travel with you, and which do not. CareShield Life and the Dependants' Protection Scheme (DPS) cover you worldwide. MediShield Life does not pay for treatment overseas.
- Why your health cover needs the closest look. Most Integrated Shield Plans (IPs) cover overseas emergencies only, which is very different from everyday medical cover where you live.
- The costs people often miss. Premiums paid from MediSave and CPF can run down when you stop contributing, and giving up cover now can make it harder to get back later.
Living overseas does not automatically mean the insurance you bought in Singapore will no longer matter. In fact, most of your policies can remain in force, even if you never return.
What could change however is how useful each policy is once you no longer reside in Singapore, and how easily you can pay premiums or make claims from abroad.
1. Review your health insurance first
Your hospitalisation/medical coverage is usually where an overseas move can create the biggest change.
MediShield Life does not cover medical treatment outside Singapore
If you are hospitalised while living overseas, MediShield Life will not pay the bill.
MediShield Life is strictly for treatments received in Singapore. If you are taking a temporary overseas posting, your policy (and premium payments) will usually remain even though it will not cover treatments in the country where you will be residing.
Only citizens who have migrated abroad for at least five years and have no intention of returning to live here can apply to suspend MediShield Life premium payments. Even so, if you do return, whatever suspended premiums you incur will have to be paid with compound interest.
Your Integrated Shield Plan provides some overseas cover
Most Integrated Shield Plans (IPs) bought in Singapore cover emergency overseas medical treatments. Your benefits will vary according to your insurer and policy.
But you should still note emergency overseas cover is not the same as comprehensive medical insurance. Check with your insurer:
- what qualifies as an overseas emergency
- whether planned treatment is covered
- overseas claim limits
- whether outpatient treatment is included
- whether there are restrictions linked to overseas residency.
If you are moving for work, compare your existing IP with your employer's medical plan before deciding whether an additional health insurance plan is needed.
2. Check how your critical illness policy handles overseas diagnosis
Critical illness coverage bought in Singapore may continue after you relocate, but you should still be aware of the claims process. Check whether:
- a diagnosis made overseas is accepted
- the doctor or medical institution you visit meet the requirements set by your insurer
- overseas medical records need certification or translation
- any geographical restrictions apply.
You should also confirm whether your change in residency or occupation needs to be declared.
3. Life insurance may continue, but review the terms
Typically, most life insurance policies bought in Singapore remain valid no matter where you reside, as long as you continue paying the premiums. This even applies to the Dependants’ Protection Scheme (DPS), the government-supported term-life policy.
However, some life insurance policies, even with so-called worldwide coverage, may contain conditions relating to:
- particular countries or regions
- higher-risk work or activities
- documentation required for an overseas claim.
You should also know that any future claims will be paid out in the original currency of the policy (in most cases, SGD, for policies bought in Singapore).
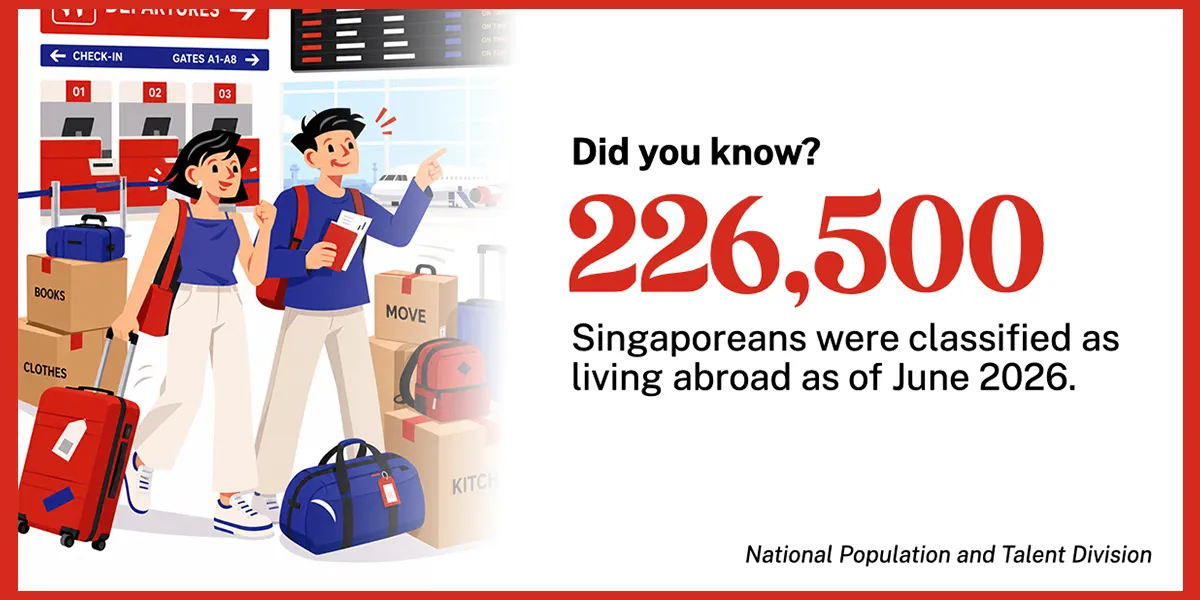
4. CareShield Life also follows you overseas
CareShield Life is another government-backed policy which provides worldwide coverage. Claims and payouts can continue even if you are living overseas, again as long as the premiums are paid.
This means you can live or retire outside of Singapore, without losing the core benefits of the policy.
5. Your investment-linked policies (ILPs) may continue, but servicing and tax can change
As ILPs are both an insurance policy and an investment, there are more things to consider as compared to pure insurance policies if you move abroad.
Firstly, you should check whether you can continue to:
- pay regular premiums from overseas
- switch investment funds
- make top-ups
- make partial withdrawals
- change insurance coverage
- access policy services.
Your new country may also tax the policy differently as compared to when you were living in Singapore. Different countries have different rules regarding foreign investments, investment gains or death benefits.
If your policy has accumulated substantial investment value and you are migrating for the long term, you may want to take local tax advice from the country you are in, rather than assuming nothing changes.
Other factors you will also have to consider include:
- your current policy value
- surrender charges
- insurance protection that would be lost
- ongoing insurance charges
- how the underlying funds have performed
- whether the policy still suits your financial goals.
6. Endowment and wealth accumulation policies can usually continue too
Relocating also does not usually mean you need to terminate your endowment or wealth accumulation plans.
Instead, check the practical details:
- how future premiums will be paid
- where maturity proceeds can be credited
- whether you need to retain a Singapore bank account
- whether withdrawals or other policy transactions can be processed overseas
- how your new country treats the proceeds for tax purposes.
If the policy is already several years into its term, understand the surrender value before making changes. Cancelling early can mean giving up benefits or receiving less than you expected.
7. Do not rely too heavily on your employer's insurance
An overseas employer may provide medical, life or accident insurance.
Before treating that as a replacement for your own cover, check:
- whether your spouse and children are included
- whether outpatient treatment is covered
- whether private hospitals are covered
- whether you are covered outside your country of posting
- whether you remain covered when visiting Singapore
- when the coverage ends if you leave the company.
That last point matters. Employer insurance usually ends when your employment ends. Your personal insurance stays with you.
So even a generous company plan should be assessed alongside, rather than automatically instead of your existing cover.
Will your CPF contributions continue when you move overseas?
Choose the situation that best describes your move. Your employment arrangement can affect whether regular CPF contributions continue while you are abroad.
What generally happens
Your CPF contributions may stop
CPF contributions are generally not payable on wages for an employee who is employed to work overseas.
What generally happens
Your CPF contributions may continue
If you remain on a Singapore-based employment contract and are working overseas only temporarily, CPF contributions generally remain payable.
What to check
Your employment arrangement matters
Check whether your employment contract remains based in Singapore, whether you have been hired specifically for an overseas role, and whether the overseas arrangement is formally temporary.
One more thing before you leave
If your CPF contributions will stop, check your MediSave balance against any insurance premiums currently paid from MediSave. Your cover may continue even when the way you fund it changes.
Source: CPF Board. CPF treatment depends on the facts of each employment arrangement. Information correct as of September 2026.
Focus on the gaps your move creates
Moving overseas does not have to necessitate you starting your insurance planning from scratch.
Some of your existing protection may continue to work well. Other policies, particularly health insurance, may become less useful where you are living.
Rather than asking what you should cancel, ask: What still works? What no longer works the way I need it to? What new gap has my move created?
That is the more useful basis for deciding what to keep, what to adjust and whether additional cover is needed overseas.
If you are unsure how a particular policy will operate after you relocate, check the policy wording or speak to your insurer or financial representative before making changes.
Written by: Great Eastern Lifepedia team
Frequently asked questions

GREAT Life Advantage
Whole life coverage with add-on critical illness protection in one flexible plan
Read more like this
Let us match you with a qualified financial representative
Our financial representative will answer any questions you may have about our products and planning.