

What is an annuity? How annuities work in Singapore
Financial Literacy 101: How annuities turn retirement savings into regular income, and where CPF LIFE fits in.
What this article covers
- What an annuity is and why payout duration matters. Learn how annuities convert savings into retirement income, and why income for 20 years is different from income for life.
- Where CPF LIFE fits in. CPF LIFE is itself a life annuity, but it works differently from annuity plans offered by private insurers.
- Why retirement income insurance is not necessarily an annuity. Two plans can both provide monthly retirement income while making very different promises about how long those payments last.
- What to check before committing your money. Understand guarantees, access to your savings, inflation, death benefits and the special tax considerations when SRS funds are involved.
We spend most of our working lives trying to build enough money for retirement.
At some point, however, an important question may arise: “How do I turn this money into income that supports me throughout my retirement?”
One way of doing this is through an annuity.
An annuity is an insurance policy that typically provides regular payments, often monthly, either for a fixed period or for as long as you live. You usually pay the premium as a lump sum or over an agreed period before the payouts begin.
How does an annuity actually work?
You build or provide the money first. Depending on the annuity you buy, this could mean either paying one lump sum or making premium payments over several years.
Your insurer then turns this accumulated pot into a stream of regular payments later.
For life annuities, your insurer pays you throughout your entire lifetime, even if you live longer than expected.
This is possible because your initial money was pooled with everyone else who bought the same plan.
- Some people in that pool may live shorter lives than expected.
- Some live longer.
- The pool absorbs the difference and thus can provide lifelong payments to even those who live past 100.
What are the different types of annuities?
Besides life annuities, there are term annuities.
- A term annuity provides regular payments for an agreed number of years (typically 10, 15 or 20)
- A life annuity provides regular payments for the rest of your life, no matter how long you live.
Imagine two people starting retirement income at 65.
One has a policy that pays for 20 years. The other has a life annuity.
- At 70, 75 and 80, both may continue receiving payments.
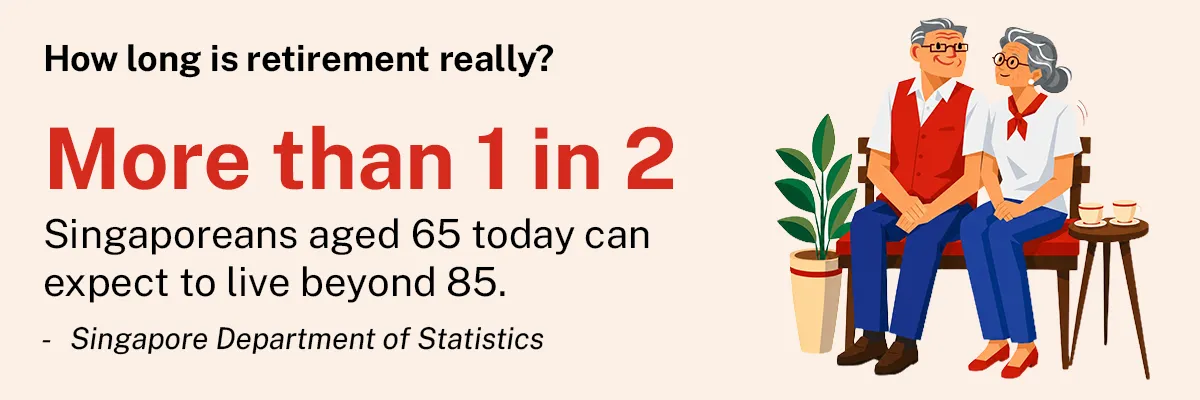
- At 85, the first policy has reached the end of its agreed payout period.
- Meanwhile, the life annuity continues paying if the policyholder is still alive.
Neither structure is automatically better.
- A fixed-term income stream may be useful when you want additional income during a particular part of retirement.
- A life annuity solves a different problem. It protects against the risk of outliving your savings.
The annuity you may already have: CPF LIFE
If you have CPF savings, you may already own an annuity.
CPF LIFE is the only life annuity (it pays monthly for as long as you live) that is fully backed by the Singapore government.
Any leftover money in your Retirement Account also goes to your nominees upon your death, meaning dying early does not mean losing out.
For many Singaporeans, CPF LIFE form the starting layer of lifelong retirement income. However, a common question many have is whether CPF LIFE can fully fund your retirement.
That is where a private annuity can come in. This is a policy purchased from an insurance company. With a private annuity, you can choose when your payout starts, how long they run (lifetime or term) and how much you put in. However, its guaranteed benefits, non-guaranteed benefits, death benefits and other features depend on the policy you buy.
Are all “retirement income insurance” annuities?
No. “Retirement income” describes what a product is intended to provide. It does not, by itself, tell you how the underlying insurance policy is structured.
- An annuity may provide income for a fixed term or for life at regular intervals (monthly, annually).
- Other insurance products can also generate retirement income. For example, some savings or endowment policies can make payments at predetermined intervals during the policy term before paying the remaining benefits at maturity. That can still be useful retirement income, but it does not necessarily provide the same protection as a life annuity.
So, instead of relying on words such as “retirement”, “income” or “monthly payout” in the product name, check the contract for one simple detail: “When does the payout end?”.
If your objective is specifically to protect against living a very long time, the answer matters.
What should you check when comparing annuities?
Some participating annuities include a guaranteed amount, alongside projected, non-guaranteed bonuses. The projection is not a promise, and it can come in lower than shown.
Before comparing two policies, check five things in each:
- The guaranteed payout. What remains even if nothing else pays out. Compare this figure first.
- The projected payout. The larger, more attractive number, usually built on non-guaranteed bonuses. Treat it as a possibility, not a plan.
- The payout period. The end date. Twenty years and for life are different products in similar language.
- What happens if you die early. CPF LIFE returns what is left in your Retirement Account to your nominees. Private plans vary, so check.
- What it costs to get out. Cashing out early usually returns less than you paid in.
Can you decode this retirement income plan?
Look at this fictional retirement income illustration, then answer three questions. The aim is not to find the “best” plan, but to know which figures matter when you compare one.
Illustrated monthly retirement income
S$2,000
S$1,400 guaranteed + S$600 non-guaranteed
For learning purposes only. This is not an actual insurance product or benefit illustration.
What are the trade-offs of annuities?
Predictable income from annuities has a price, not paid in premiums, but paid in access.
A regular income stream through annuities will generally not help if you suddenly need a large lump sum for an unexpected expense like a roof repair, a medical bill, or a child who needs help with a flat deposit. Cashing out your annuity early also usually means a loss, and you cannot normally borrow against the policy.
As such, it is generally advised to buy an annuity only if you can afford to hold it for the long term. You should also consider keeping different pools of money for different roles.
- Predictable income. CPF LIFE and/or a private annuity
- Liquidity. Cash and other readily accessible savings
- Potential longer-term growth. Suitable investments
How you divide your money between these roles depends on your circumstances, spending needs and tolerance for uncertainty.
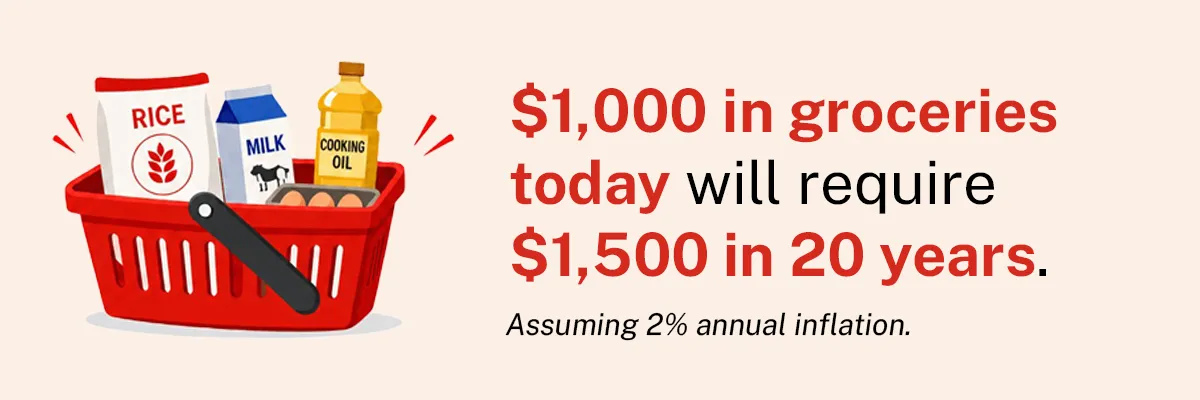
Does an annuity keep up with inflation?
Not necessarily. Often, it depends on the policy you have chosen and its stated benefits and payouts.
CPF LIFE, as an annuity, demonstrates this.
- Its Standard Plan provides steady payouts from the time you retire.
- Its Escalating Plan increases payouts by 2% each year for life.
Assuming inflation is at or below 2% annually, the Escalating Plan can offset the effects of rising prices, but the trade-off is lower initial payouts compared to the Standard Plan.
For private annuity plans, you should check whether the payout:
- Stays level.
- Rises by a guaranteed amount.
- Includes only projected increases.
- Follows another structure specified in the policy.
Do not assume that an illustrated increase is guaranteed.
Are annuity payouts taxed in Singapore?
Generally, annuities received in Singapore are not taxable. However, there are exceptions, which are annuities:
- Arising from a trade, business or profession.
- Purchased by your employer in place of pension or other employment benefits.
- Involving your Supplementary Retirement Scheme (SRS) savings.
SRS-funded annuities require additional care.
For qualifying SRS withdrawals after the prescribed retirement age, generally 50% of each withdrawal is subject to tax, and withdrawals can normally be spread over 10 years.
Life annuities are treated differently. The normal 10-year withdrawal period does not apply to the life annuity itself. Before your SRS account is closed or deemed closed, annuity payments paid into the account are not taxed if no withdrawal is made. After the account is closed or deemed closed, 50% of subsequent life-annuity payments is subject to tax each year.
This can change when your retirement income becomes taxable, so check the prevailing SRS rules when comparing your options.
Why should I get a private annuity if I already have CPF LIFE?
For most Singaporeans, CPF LIFE gives you a foundation or basic floor for retirement. What private annuities and other forms of retirement income do is to fill any monetary gaps you have for the retirement lifestyle you want.
If you are considering a private annuity or retirement income insurance plan, a financial representative can help you understand how it may fit alongside CPF LIFE and your other retirement resources.
Remember: different retirement assets solve different problems.
- Life annuities can protect against living longer than expected and raises your retirement income floor.
- Cash provides access to money when you need it.
- Investments can provide flexibility and potential long-term growth.
The aim is not to find one product that does everything. It is to build a retirement plan in which different sources of money can continue performing the jobs you need them to do.
Frequently asked questions
Read more like this
Let us match you with a qualified financial representative
Our financial representative will answer any questions you may have about our products and planning.