

How Singapore's new retirement age affects your CPF and SRS
Financial Planning 101: The statutory retirement and re-employment ages changed in July 2026. Here is what it may mean for your retirement plan.
What this article covers
- What the 1 July 2026 changes to the retirement and re-employment ages actually does. Understand how the retirement and re-employment ages differ from CPF withdrawals at 55 and CPF LIFE payouts from 65.
- How working longer could reshape your income rather than simply extend your existing job. Find out what may change in your role, salary, hours, benefits and CPF contributions, and what to clarify before accepting a re-employment offer.
- Why the timing of your Supplementary Retirement Scheme (SRS) withdrawals, insurance review and retirement income matters. Learn which decisions become fixed, how continued employment could affect tax and what to prepare for if work ends earlier than expected.
Since 1 July 2026, Singapore's statutory retirement age has risen from 63 to 64. The re-employment age has also gone up to 69 (from 68 previously).
For someone approaching retirement, this could mean another year of earnings, more time to save, or an opportunity to move into a less demanding role. However, it does not change when CPF LIFE payouts can begin, and it does not guarantee the same job or salary until age 69.
This article explains everything affected by the changes in the retirement and re-deployment ages and explores how you can adjust your own retirement plan.
Background: understanding the changes on 1 July 2026
The new retirement age means your employer cannot dismiss you based on your age if you have not turned 64. This applies to employees born on or after 1 July 1963.
The new re-employment age of 69 applies to employees born on or after 1 July 1958. Your employer must offer to re-employ you each year up to 69 if you meet these criteria set by the Ministry of Manpower (MOM):
- You are a Singaporean citizen or Permanent Resident (PR).
- You have served your current employer for at least 2 years before turning 64 for employees hired at age 55 and above
- You have satisfactory work performance, as assessed by your employer.
- You are medically fit to continue working.
Both ages fall under the Retirement and Re-employment Act, which applies only to Singaporeans and PRs. Employees on work passes are not covered. Singapore has set a goal to raise both ages to 65 and 70 respectively by 2030.
How the changes may affect your job, salary and benefits
It is important to note that neither ages are fixed timelines for when you should stop working.
- You can retire earlier than 64 if you want.
- You can also work past 69 if you and your employer agree. Re-employment age is an obligation on your employer’s part to continue offering you a role up till 69.
However, neither milestone also guarantees you the same job at the same pay. Your employee can legally offer you a different role or lower salary.
The MOM advises that any such adjustments should reflect reasonable factors like job scope, workload, productivity, performance and the company’s wage system.
In its Tripartite Guidelines on the Re-employment of Older Employees, the MOM also states such offers should be based on genuine changes to the job and not used as pressure for the employee to leave.
Employers are encouraged to begin re-employment discussions at least six months before the retirement date and make an offer at least three in advance.
Before accepting to any arrangement with your employer, you should clarify:
- Your responsibilities, working hours and training for the role.
- Your basic salary, bonuses and expected take-home pay.
- Your medical benefits, insurance coverage and leave.
- The contract duration, renewal arrangements and notice terms.
Do not assume your existing salary and benefits will continue unchanged until 69. Concurrently, if you making a retirement plan, your budget should be based on the new terms actually offered.
If you are eligible for re-employment but your employer cannot offer you a suitable position, then your employer must:
- Transfer the re-employment obligation to another employer, with your agreement, OR
- Offer you a one-off Employment Assistance Payment (EAP).
Three-question quiz
How well do you know Singapore's older workforce?
Working for longer is becoming more common, but what does it look like in practice? Test yourself against the latest official figures.
Longer careers are becoming more common, but job continuity, employment terms and skills preparation can still differ from person to person.
Does the higher retirement age change when your CPF pays out?
The CPF Board has confirmed that CPF LIFE payout eligibility age remains separate to the new retirement and re-employment ages.
- Age 55: your Retirement Account (RA) is created. You may withdraw a lump sum, subject to setting aside your retirement sum. Unchanged.
- Age 64: the earliest age your employer may retire you. Raised from 63.
- Age 65: CPF LIFE payouts may begin. You may defer to 70. Unchanged.
- Age 69: the limit of your employer's re-employment obligation. Raised from 68.
CPF contributions continue while you remain an eligible employee, but the contribution rates vary by age. For some older workers, your CPF contribution rates may change starting next year:
- 55 and below: 37%, unchanged
- Above 55 to 60: 34%, rising to 35.5% in January 2027
- Above 60 to 65: 25%, rising to 26% in January 2027
- Above 65 to 70: 16.5%, unchanged
- Above 70: 12.5%, unchanged
Your employer will absorb 0.5 percentage points of the 2027 increase if you are in the two affected age bands. The remaining (1 percentage point for those aged 56 to 60, and 0.5 percentage points for those aged 61 to 65) will have to come from you.
This means your take-home pay may dip slightly next year even without a pay cut. The increase in contributions will also be allocated to your RA until you reach the Full Retirement Sum (FRS). Only if you have already set aside the FRS, will it go to your Ordinary Account (OA).
Should you defer your CPF LIFE payouts if you continue working?
You can start CPF LIFE payouts at any point from 65 to 70.
If your employment income can cover your expenses, you may opt to defer your CPF LIFE payouts as they increase the later you choose to receive them. Payouts can rise by up to 7% for each year of deferment, or up to 35% if you wait until 70.
On the flip side, starting your CPF LIFE payouts earlier may be more practical if you need the funds to supplement a reduced salary or cover higher healthcare and household expenses. A higher future payout must be weighed against the payouts you give up during the deferment period.
Otherwise, you may also wish to consider if savings, investments or a retirement income plan may help you cover the difference if CPF LIFE does not provide the monthly income you want.
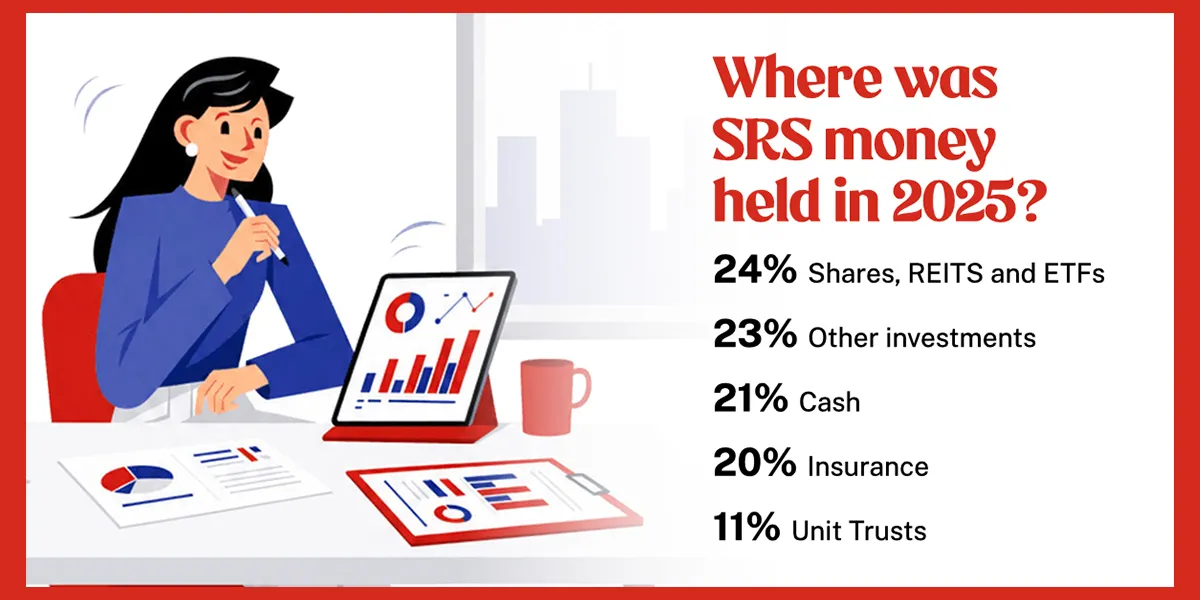
How does the higher retirement age affect your SRS?
This is where the July 2026 date may genuinely matter. Your penalty-free SRS withdrawal age is fixed at the statutory retirement age in force when you made your first SRS contribution.
- First contribution before 1 July 2022: your penalty-free withdrawal age is 62
- First contribution between 1 July 2022 and 30 June 2026: the age is 63
- First contribution from 1 July 2026: 64
Even if you have contributed a small amount (like S$1) into your SRS account before July 2026, the start of your penalty-free SRS withdrawal does not change. The changes only applies to individuals who did not make any contributions before 1 July 2026.
Your first penalty-free retirement withdrawal starts a 10-year withdrawal period. Any balance remaining at the end of that period is generally deemed to have been withdrawn, although different treatment applies to life annuities.
Once you begin withdrawing on retirement or medical grounds, you can no longer make further SRS contributions. This makes the timing of your first withdrawal especially important.
If you are still earning a salary, the taxable portion of an SRS withdrawal will be added to your other taxable income. Spreading withdrawals across lower-income years may therefore result in less tax than withdrawing large amounts while you are still working.
Read our complete SRS guide, for more details about the contribution and withdrawal rules.
Other retirement measures worth knowing
The following measures are separate from the higher retirement and re-employment ages but may also affect your retirement planning.
- Matched Retirement Savings Scheme: dollar-for-dollar matching on cash top-ups to your Retirement Account, up to $2,000 a year and $20,000 over a lifetime, for eligible members.
- Matched MediSave Scheme: from January 2026 for five years, matching voluntary MediSave top-ups dollar for dollar up to $1,000 a year for eligible citizens aged 55 to 70.
- Budget 2026 CPF top-up: eligible Singaporeans aged 50 and above with retirement savings below the Basic Retirement Sum are due up to $1,500 in December 2026, tiered by savings and property annual value.
- CPF life-cycle investment scheme: Announced during Budget 2026 this is a new, voluntary retirement investment option scheduled to be launched in the first half of 2028. The scheme is designed for CPF members who want to take on investment risk for higher potential returns but prefer a hands-off, simplified approach compared to the existing CPF Investment Scheme (CPFIS). Investment risks still apply.
Does working longer affect your income tax?
You may received more Earned Income Relief as you grow older:
- Below 55: up to S$1,000.
- Age 55 to 59: up to S$6,000.
- Age 60 and above: up to S$8,000.
The amount is based on your age as of 31 December the previous year and is capped at your taxable earned income. It is generally granted automatically.
It is important to know that this relief reduces the income on which tax is calculated and does not directly reduce your tax bill by the same dollar amount.
Why you should check your medical and insurance coverage before your retirement
Even if you continue working past the retirement age, your company’s medical benefits can change under a re-employment arrangement.
Depending on the terms of your contract, your employer may continue existing benefits, introduce co-payments or claim limits, or provide additional MediSave contributions or other flexible benefits.
Ask your employer:
- Whether your group medical and insurance coverage will continue.
- Whether the claim limits, co-payments or covered treatments will change.
- When the coverage will end.
- Whether additional MediSave contributions will be provided.
Do not assume that working longer automatically extends the same group coverage. You should check what your personal insurance provides if your employer benefits change or end.
If you hold an Integrated Shield Plan, consider whether its premiums will remain affordable as you get older. If necessary, moving to a plan covering a lower ward class with the same insurer may reduce the cost without requiring fresh underwriting.
Review this before leaving employment. Changes in health could affect the terms available if you later apply for new private coverage.
Make working longer an option, not a necessity
Higher retirement and re-employment ages may give you more opportunities to keep earning, but they do not guarantee more retirement income or savings in the future. Health issues, caregiving responsibilities or a lack of suitable work for instance could easily bring your employment to an earlier end than what you may have hoped.
As such, treat any potential additional working years as a way to strengthen the existing retirement plan you may already have, rather than depend on them to make your retirement work.
A financial representative can help you assess whether your income, savings and protection arrangements support your retirement, no matter what age it ultimately begins.
Frequently asked questions
Let us match you with a qualified financial representative
Our financial representative will answer any questions you may have about our products and planning.