


See how Lifetime Boost works
Your questions answered for Lifetime Boost
Lifetime Boost is a regular premium participating endowment insurance plan with a limited premium payment term of 5 years and a policy term of 100 years.
It provides yearly payouts, comprising a guaranteed survival benefit and non-guaranteed cash bonuses (if any), from the end of 3rd policy year onwards. The actual yearly payout will depend on the guaranteed survival benefit and any non-guaranteed cash bonus declared by us.
This plan provides financial protection against death and terminal illness throughout the policy term and pays a maturity benefit when the policy matures.
As a participating plan, it allows you to take part in the performance of the participating fund through non-guaranteed bonuses.
This plan provides the option to transfer policy ownership and life assured status across generations under the Universal Wealth Transfer Option (UWTO), subject to the applicable terms and conditions.
In addition, the policy provides a capital guarantee¹ from the end of policy year 6 for annual premiums of S$20,000 and above, or from the end of policy year 8 for annual premiums below S$20,000.
¹ Capital guarantee is on the condition that all premiums are fully paid and no policy alterations have been made.
Lifetime Boost provides the following coverage:
Benefits | Coverage |
Death Benefit | 101% of Total Standard Annual Premiums Paid2 + bonuses (if any), less any debt. |
Terminal Illness Benefit | Pays the Death Benefit in one lump sum upon a conclusive diagnosis of an illness that is expected to result in the life assured’s death within 12 months of the diagnosis, subject to the Terminal Illness Benefit Limit3. |
The plan shall terminate once the full death benefit or maturity benefit has been paid, whichever occurs first.
There are other situations where the plan will terminate.
Please refer to the product summary and policy contract for more details.
2 Total Standard Annual Premiums Paid” refers to the aggregate amount of Standard Annual Premiums that have become due and been paid under this Policy, up to a maximum of five (5) years of Standard Annual Premiums, or up to the next Policy Anniversary following the death of the Current Life Assured or date of diagnosis of Terminal Illness, whichever occurs first. For the avoidance of doubt, any Standard Annual Premium that has not yet fallen due under this Policy shall not be included in the Total Standard Annual Premiums Paid. Proportional revision of the Total Standard Annual Premiums Paid will apply when there is a partial surrender of this Policy.
3Terminal Illness Benefit Limit refers to the total terminal illness benefit payable which is limited to $20,000,000 (in absolute dollar terms and regardless of currency) under this and all policies and riders issued by us giving similar benefits, based on the same life assured.
This plan provides both guaranteed and non-guaranteed benefits:
- Guaranteed benefits, including bonuses which have already been declared, will be paid regardless of how the participating fund performs.
- Non-guaranteed benefits are in the form of future bonuses, which have yet to be declared and are dependent on the performance of the participating fund. These bonuses are not guaranteed.
There are two main types of non-guaranteed bonuses for this plan:
- cash bonus; and
- terminal bonus.
Please refer to the product summary and policy contract for more details.
From the end of the 3rd policy year onwards, we will provide a yearly payout at the end of each policy year until:
- (a) a claim is admitted whereby the full Death Benefit is paid out;
- (b) the policy matures; or
- (c) the plan is terminated,
whichever occurs first.
Each yearly payout consists of:
- a guaranteed survival benefit; and
- a non-guaranteed cash bonus that may be declared yearly (if any).
The actual yearly payout amount will depend on the guaranteed survival benefit and any cash bonus declared by us. As cash bonuses are not guaranteed, the actual yearly payout amount may vary from year to year.
You may withdraw these payouts or keep them with us to earn non-guaranteed interest. Please note that the non-guaranteed interest is subject to change without prior notice. If there is any debt attached to the policy at the time we are due to pay the payouts, we will first use these payouts to reduce any debt you have with us before the balance amount is paid.
The Universal Wealth Transfer Option (UWTO) allows for the transfer of policy ownership and life assured status, subject to the applicable eligibility criteria, terms and conditions.
The policy may continue across generations within its 100-year policy term.
At any time after the free-look period and while the policy is in force, provided that all recurring premiums due and payable for the Policy over the entire premium term have been fully paid, the current policyholder4 may request in writing to either:
- Option A: Effect a change in policyholder and life assured while the current policyholder4 is still alive; or
- Option B: Appoint a Policy Successor5, where the change in policyholder and life assured shall be effected upon the death of the current life assured4.
Please refer to the product summary and policy contract for more details.
4 Current policyholder, who is also the current life assured, refers to the person who is both the policyholder and life assured of the policy as at that point in time.
5 Refers to a person appointed by the current policyholder to be the new policyholder and life assured for the policy in exercise of the Universal Wealth Transfer Option. This allows for the continuity of the policy upon the death of the current policyholder and life assured, provided that the appointment has not been revoked or invalidated on or prior to the death of the current policyholder and life assured.
You will receive an annual bonus update that will include the following:
- The performance of the participating fund and its future outlook, which you should receive around the second quarter of each year after the bonus is declared for the policy; and
- An annual statement regarding bonuses for the policy, which you should receive around the second quarter of each year after the bonus is declared for the policy. For policies with cash bonus, you should receive the relevant statement within one month from your policy anniversary only when the cash bonus is due.
When there is a change in the rate of bonuses declared, you can ask for an update of the illustrated values.
If you surrender your policy after the 14-day free-look period, you may lose part or all of the premiums paid. This is because the surrender value, if any, that is payable to you may be zero or less than the total premiums paid.
Lifetime Boost provides both guaranteed and non-guaranteed benefits. Future cash bonuses and terminal bonuses are not guaranteed and depend on the future performance of the participating fund.
As buying a life insurance policy is a long-term commitment, an early termination of the policy usually involves high costs and the surrender value, if any, that is payable to you may be zero or less than the total premiums paid.
Please refer to the product summary and the policy contract for more details. Alternatively, you may also speak to your financial representative or call us at 1800 248 2888 (Monday to Friday, 9am to 5.30pm).
Your questions answered for Lifetime Boost Rider
The Lifetime Boost Rider is an optional single premium non-participating endowment rider with a rider term of 4 years that can be attached to your Lifetime Boost base plan at policy inception, provided your Lifetime Boost policy is issued with annual premium payment mode selected. It provides financial protection against death and terminal illness and pays a guaranteed yearly payout at the end of the 12th, 24th, 36th and 48th policy months while the rider is in force.
Each guaranteed yearly payout will be automatically applied towards the payment of the annual premium due under the Lifetime Boost policy to which this rider is attached.
At the end of the 4-year rider term, the rider matures and pays a guaranteed maturity benefit based on the applicable maturity benefit rate secured at policy inception, less any debt under the policy, if applicable.
The Lifetime Boost Rider is available only when you apply for a new Lifetime Boost policy. It is not available as an add-on to an existing Lifetime Boost policy.
If you surrender your policy and/or its attached rider after the 14-day free-look period, you may lose part or all of the premiums paid. This is because the surrender value, if any, payable to you may be zero or less than the total premiums paid.
If you surrender only the Lifetime Boost Rider, the attached Lifetime Boost policy will remain in force, subject to its terms and conditions. You will be responsible for paying all future premiums due under the Lifetime Boost policy when they fall due. Failure to do so may result in the policy lapsing.
Partial surrender of the Lifetime Boost Rider is not allowed.
No. The Lifetime Boost Rider is a non-participating rider and does not participate in the profits of the participating fund. It is not entitled to bonuses.
Understand the details before buying
The two IIRRs used (3.00% p.a. and 4.25% p.a.) are purely illustrative and do not represent lower and upper limits of the participating fund. The actual benefits payable will depend on the actual performance of the participating fund. The performance of the funds is not guaranteed and the surrender value may be less than the total premiums paid.
1 The prevailing accumulation interest rate is 3.00% p.a. based on an IIRR of 4.25% p.a. and 1.50% p.a. based on an IIRR of 3.00% p.a. This rate is not guaranteed.
2 Subject to policy terms and conditions, provided all recurring premiums have been paid for the policy as they fall due, you may request to transfer policy ownership and life assured status during your lifetime or appoint a Policy Successor through the Universal Wealth Transfer Option (UWTO), subject to the Company's approval. If successfully exercised, the policy will continue based on the original date of commencement.
3 The policy matures 100 years from the date of commencement. If the life assured at that point in time is alive when the policy matures, the maturity benefit payable is equal to the guaranteed surrender value for the final policy year plus bonuses (if any), less any outstanding debt under the Policy.
4 The Lifetime Boost Rider is an optional single premium non-participating endowment rider with a rider term of 4 years that can be attached to your Lifetime Boost policy at policy inception, provided the Lifetime Boost policy is issued with annual premium payment mode. If the Lifetime Boost Rider is surrendered, the policyholder at that point in time must continue to pay all premiums that fall due under the Lifetime Boost policy after the surrender, to keep the policy in force.
5 The rate of the guaranteed maturity benefit for your Rider will be based on the applicable rate on the date you submitted the application, assuming your policy is paid for and in force. The Company reserves the right to amend the Rider’s rates payable for the maturity benefit at any time without prior notice. Such amendments will not affect any applications which have been submitted or policies that are in-force. The Company also reserves the right to invalidate any application where both Lifetime Boost and Lifetime Boost Rider have not become in force within 7 days from the date of application submission. You should refer to your policy documents for the applicable maturity benefit rate or approach your Financial Representative for more information on the prevailing maturity benefit rate.
6 Capital is guaranteed from the end of policy year 6 for policies with annual premiums of S$20,000 and above, or from the end of policy year 8 for policies with annual premiums below S$20,000, on the condition that all premiums are fully paid and no policy alterations have been made.
* Refer to the table below for the breakdown of the guaranteed and non-guaranteed benefits. As bonuses are not guaranteed, actual benefits payable may vary according to the future performance of the Participating Fund.
For annual premiums of S$20,000 and above:
IIRR (p.a.) | Guaranteed benefit (p.a.) | Non-guaranteed benefit (p.a.) | Total yearly benefit (p.a.) |
From the end of policy year 3 to the end of policy year 8 | |||
4.25% | 0.80% | 1.50% | 2.30% |
3.00% | 0.80% | 0.81% | 1.61% |
From the end of policy year 9 onwards | |||
4.25% | 0.80% | 2.55% | 3.35% |
3.00% | 0.80% | 1.38% | 2.18% |
For annual premiums below S$20,000:
IIRR (p.a.) | Guaranteed benefit (p.a.) | Non-guaranteed benefit (p.a.) | Total yearly benefit (p.a.) |
From the end of policy year 3 to the end of policy year 8 | |||
4.25% | 0.76% | 0.79% | 1.55% |
3.00% | 0.76% | 0.43% | 1.19% |
From the end of policy year 9 onwards | |||
4.25% | 0.76% | 2.39% | 3.15% |
3.00% | 0.76% | 1.29% | 2.05% |
‡ Based on an IIRR of 3.00% p.a.,
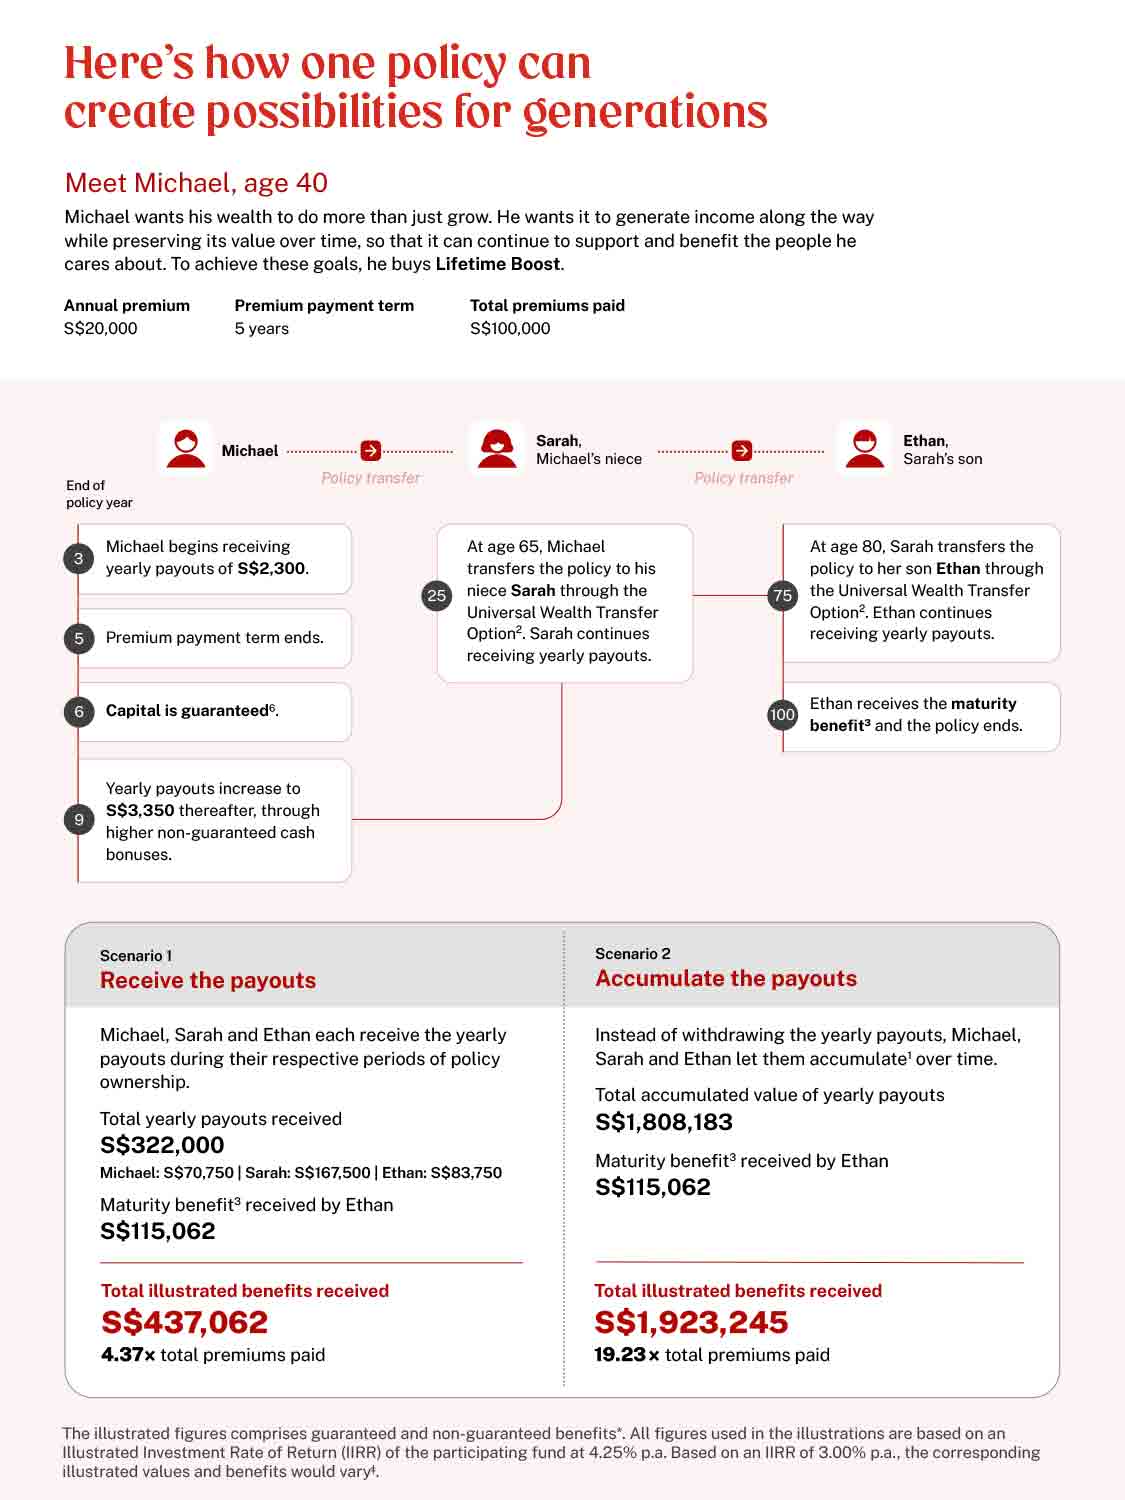
The yearly payout would be S$1,610 from the end of policy years 3 to 8 and S$2,178 from the end of policy year 9 onwards.
In scenario 1, the total yearly payouts received would be S$210,036 (Michael: S$46,686 | Sarah: S$108,900 | Ethan: S$54,450). Including the maturity benefit of S$108,556 received by Ethan, the total illustrated benefits received would be S$318,592 (3.19x total premiums paid).
In scenario 2, the total accumulated yearly payouts would be S$465,532. Including the maturity benefit of S$108,556 received by Ethan, the total illustrated benefits received would be S$574,088 (5.74x total premiums paid).
All ages specified refer to age next birthday.
All figures used are for illustrative purposes only and are subject to rounding.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
The above is for general information only. It is not a contract of insurance or a recommendation to buy an insurance product or service. This document does not take into account the specific investment and protection aims, financial situation or particular needs of any particular person. You may wish to seek advice from a financial adviser before making a commitment to purchase this product. If you choose not to seek advice from a financial adviser, you should consider whether this product is suitable for you.
The terms, conditions and exclusions of this insurance plan are specified in the policy contract. If you are interested in the insurance product, you should read the product summary and policy illustration (available from us) before deciding whether to buy this product.
As buying a life insurance policy is a long-term commitment, an early termination of the policy usually involves high costs and the surrender value, if any, that is payable to you may be zero or less than the total premiums paid.
This policy is protected under the Policy Owners’ Protection Scheme which is administered by the Singapore Deposit Insurance Corporation (SDIC). Coverage for your policy is automatic and no further action is required from you. For more information on the types of benefits that are covered under the scheme as well as the limits of coverage, where applicable, please contact us or visit the Life Insurance Association (LIA) or SDIC websites (www.lia.org.sg or www.sdic.org.sg).
In case of discrepancy between the English and the Chinese versions, the English version shall prevail.
Information correct as at 6 October 2026.
Need to speak to someone about this product?
Fill in your details and our Financial Representative will get in touch with you within 3 working days
Enhance your coverage
Check out products that supplement your coverage on top of what Lifetime Boost provides
Understanding retirement